It is clear that the country is facing a difficult fiscal landscape, as the war in Iran continues to push up inflation and borrowing costs rise globally – both eating into the Government’s fiscal headroom. All of this is well-known and well-documented.
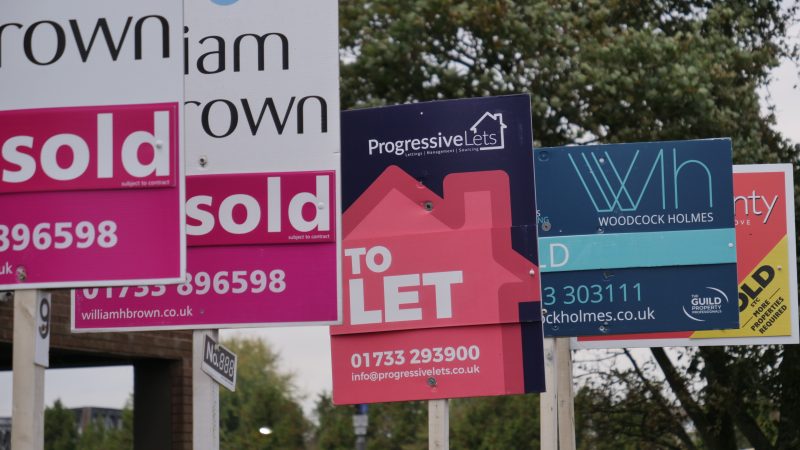
What is less well known, is the quiet crisis that has left many housebuilders feeling that their current outlook is worse than in 2008 – something builders have been telling me is stopping them from building the homes we need. The main problem is the lack of demand, particularly for first time buyers. Young people want to get on the housing ladder, but for those who can’t rely on the bank of mum and dad, few now have the means to do so.
This is a progressive cause that should not be missed out if we want home ownership to be affordable for all young people, regardless of their family background.
Much has been made of the stalling housebuilding market, with concerns that we may not hit our 1.5 million homes target. The Labour Government has introduced a range of really welcome supply-side measures to stimulate housebuilding – from the Planning and Infrastructure Act to a range of reforms in the National Planning Policy Framework. However, housebuilders are telling me that they are struggling to sell the homes they have built, stopping them buying sites and helping the government towards our target. We can help to unlock this through demand-side measures, in the form of first-time buyer mortgage assistance.
READ MORE: Labour Party Conference 2026: Full LabourList events programme, revealed
Research released this week from the Ministry of Housing, Communities and Local Government (MHCLG) found that the Help to Buy scheme, introduced in 2013, represented “very high value for money”, costing £3.6bn and generating £25.1bn in social value, or nearly £7 for every £1 spent. This ultimately strengthens the fiscal case for another mortgage assistance scheme.
The evaluation did find that Help to Buy scheme was not without flaws, suggesting that some users of the scheme were using it to purchase larger, better or preferred properties, and that there were some regional disparities in terms of impact.
A future scheme should reflect where the Prime Minister is taking the country. With mayors set to gain real control over housing and local growth funding through the ‘Rewiring the State’ agenda, a new scheme should be calibrated to local prices and incomes rather than run as a single national product from Whitehall, with mayors given a say over how it is targeted in their areas.
The coming Autumn Budget would be an ideal moment for the Government to introduce a new form of support for first-time buyers.
There is no shortage of ideas on the table. The Social Market Foundation has a “Citizens Advance”, allowing younger people to access a £12,500 lump sum equivalent to one year of their future State Pension to help fund major life milestones such as a home purchase.
Become a friend of LabourList and join our community. Our friends support our vital non-factional work and get access to exclusive content and events.
The proposal I have been most closely involved with is “” (MLTO), which I attended the launch of in Parliament in March this year. Developed by Weston Homes and TYI Strategy, MLTO would provide eligible first-time buyers with a Government-backed equity loan of up to 20% of a property’s value, interest free for five years, with developers rather than taxpayers covering the financing costs. For a buyer purchasing at £350,000, that is around £500 a month better off than on a standard 95% mortgage.
Ministers and think tanks are increasingly looking to public financial institutions, or PuFins, as a way to invest without adding to the national debt in the way conventional spending does. These bodies deploy public money through loans, equity and guarantees rather than grants, and since the 2024 move to measure debt against Public Sector Net Financial Liabilities, the assets they hold are treated more favourably than ordinary capital spending.
The Resolution Foundation has how they could help the Prime Minister square the fiscal rules with his promise of a higher-investment economy. For housing, the vehicle already exists. The National Housing Bank, launched in March with £16bn of debt, equity and guarantees behind it, was built to crowd in private investment where the market will not move alone. Its focus so far has been supply, but there is no reason in principle why a first-time buyer equity loan could not run through it. A scheme like My Loan to Own, where developers rather than taxpayers carry the financing cost, is exactly the kind of instrument a PuFin is designed to hold: an asset generating a return, not a line of departmental spending.
The precise solution is open for debate, but there is a clear opportunity for government to do more to support aspiring homeowners. If we are serious about extending homeownership and delivering the homes the country needs, some form of targeted support for first-time buyers will be required.
Subscribe here to our daily newsletter roundup of Labour news, analysis and comment– and follow us on TikTok, Facebook. You can also write to our editor to share your thoughts on our stories and share your own. The best letters are published every Sunday.
Mike Reader is the Labour MP for Northampton South and member of the Energy Security and Net Zero Select Committee.
View all articles by Mike Reader MP